
Macro Cycle
Semi Inventory Days Drop Below 90, Restocking Cycle Officially Begins
When semiconductor industry inventory days fall below the 90-day threshold, it’s more than a statistic — it’s a signal. After several years of volatile demand, over-ordering, and aggressive destocking, the recent decline in inventory days below 90 indicates the broad channel, distributor, and supplier stock positions are lean enough to trigger a deliberate restocking cycle. For investors, OEMs, procurement teams, engineers, and policymakers, the implications are material: lead times will lengthen for constrained parts, prices may firm in select segments, and capacity planning will shift from defensive idling toward targeted expansion.
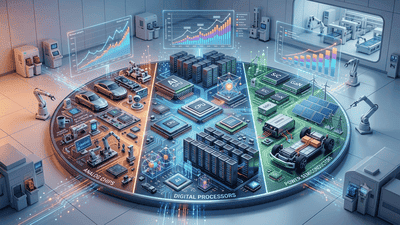
Intensifying Semi Sector Divergence: The Trilogy of Analog, Digital, and Power
The semiconductor industry is no longer a single, unified story. Instead, it is increasingly a trilogy—three distinct but interdependent sectors whose economics, technology roadmaps, and demand cycles are diverging: analog, digital, and power. On the surface, all three deal with silicon and electrons; in practice, they respond to different customer needs, move at different speeds, and face different constraints.
The Impact of 2026 Semi Industry ESG Ratings on Financing Costs
By 2026, environmental, social, and governance (ESG) metrics have moved from the margins of semiconductor boardroom discussions to the center of capital‑markets conversations. Investors, lenders, and rating agencies now routinely bake ESG scores into their assessment of risk and return. For a capital‑intensive industry like semiconductors—where fabs cost tens of billions of dollars and balance sheets carry large debt loads—the way ESG ratings influence financing costs is no longer a theoretical concern.
The "Bullwhip Effect" in Semis – Which Stage Are We In?
The semiconductor industry is famous for its cycles, but behind those ups and downs lies a deceptively simple dynamic: small changes in end demand can amplify into huge swings in orders, capacity, and inventory further up the supply chain. This phenomenon is widely known as the bullwhip effect—and in semis, it is particularly powerful. Understanding where we are in the bullwhip sequence is crucial for chipmakers, OEMs, distributors, and investors who want to avoid being caught on the wrong side of the next swing.
Japan’s Semi Renaissance: Joint 2nm R&D Progress Among 8 Major Giants
Japan’s semiconductor industry is experiencing a genuine renaissance. After decades in which the country’s role shifted from dominant memory and logic supplier to more specialized niches in equipment, materials, and certain devices, a new wave of coordinated effort is pushing Japan back toward the leading edge of process technology.
Interpreting the Sentiment Signal as Wafer Fab Utilization Breaches 85%
Wafer fab utilization is one of the semiconductor industry's most closely watched operational metrics. When utilization climbs above key thresholds, it has ripple effects across pricing, lead times, equipment demand, supplier margins, and market sentiment.
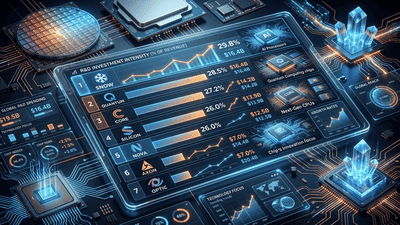
R&D Intensity Ranking in Semis: Who Keeps Doubling Down on the Future?
In semiconductors, research and development is not just a line item—it is the engine that determines who sets the pace of technology and who follows. R&D intensity, usually measured as R&D spending as a percentage of revenue, reveals how aggressively companies are investing in their future versus harvesting their present.
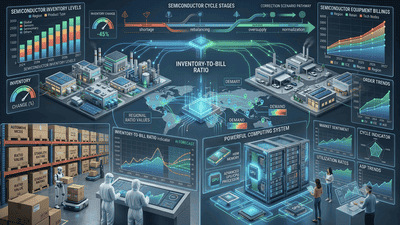
Practical Application of the Inventory-to-Bill Ratio in Semi Industry
Semiconductor executives and investors spend a lot of time staring at numbers, but not all metrics are equally useful for understanding where the cycle is heading. Among the more practical indicators is the inventory‑to‑bill ratio: a simple comparison of how much product is sitting in stock versus how much is actually being billed to customers over a given period.
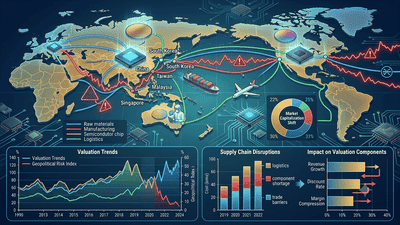
A Quantitative Model for Geopolitical Risk Premium in Semi Valuations
Geopolitics has moved from background noise to a central driver of semiconductor valuations. Export controls, regional subsidy races, onshoring mandates, and cross‑border M&A scrutiny all alter cash‑flow expectations and capital‑allocation decisions in ways traditional models often treat qualitatively, if at all.
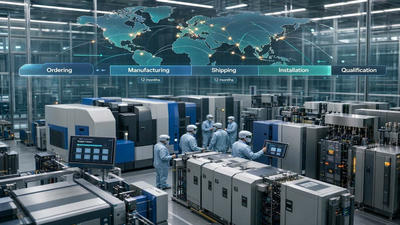
Semi Equipment Procurement Lead Times Extended to 12 Months
In semiconductor manufacturing, time is as critical a resource as capital. When lead times for key tools stretch from a few months to a full year, the ripple effects can reshape fab build schedules, technology roadmaps, and industry supply dynamics. The extension of equipment procurement lead times toward the 12‑month mark is more than an operational inconvenience;